How Challan APIs Power Fintech Innovation: Faster Onboarding and Lower Fraud
I owe a founder an apology, and this post is partly it.
Two years ago he asked me whether traffic fine data was worth adding to his onboarding stack. I told him no. Fines are small money, borrowers pay them or don't, what does a lender care. He runs a company financing two-wheelers for gig riders, six cities, tickets under a lakh. He went ahead anyway, put a Challan API into trial mode, and about four months in he forwarded me a case file with the subject line "so about that."
The application was for a loan against a scooter. Eight months old. Personal use, office commute, said the form. Ownership in the applicant's name, correct model, valuation nothing strange. Under his old process this would have sailed through the same day, and I'd have called it a good clean file myself.
Nineteen challans in eight months.
That was the trial check's finding, and even that isn't damning on its own, people collect fines. What did it was the pattern. Almost every fine logged between 1am and 3am. Almost every one near the same wholesale market. In a city two hundred kilometres from the home address on the form. His risk analyst put the timestamps on a map and the map said: this scooter works nights for a living, in a place its owner doesn't live.
They rang the applicant. There was a pause on the line, the kind that answers the question before any words do. The scooter had been rented to a delivery contractor months back. Registration still in his name, vehicle long gone from his life. He was raising money against something he technically owned and practically didn't.
Ownership check: passed. Identity check: passed. Only the fines knew.
What the fines actually tell a fintech
So here is the thing I got wrong two years ago, stated as plainly as I can manage.
I thought challan data was about the fines. It isn't. The rupee amounts are the least of it. A challan records that a specific vehicle was at a specific place at a specific time doing a specific wrong thing, and once you have twenty of those, you have something no application form gives you: a diary of how the vehicle actually gets used. The applicant writes fiction on the form. The vehicle keeps a diary.
Who reads it, and for what, differs. My founder friend reads it for collateral truth. An insurer would read the same data for pricing, since the rider with thirty violations and the rider with none currently pay nearly the same premium, which is absurd and won't last. Mobility platforms read it at driver onboarding. And portfolio teams, this one I learned from the banking collateral story, watch for spikes on financed vehicles, because a machine that abruptly starts collecting violations is generally being flogged by someone who has stopped planning for its future.
Also, at the boring end of it, pending fines are simply money owed against the asset. A vehicle challan verification API for fintech shows the outstanding amount in seconds. His team nets it off the disbursal or asks the seller to clear it. No drama in that part. Just arithmetic.
Challan API for fintech onboarding
Do you know what his onboarding used to do about driving history? I'll tell you, because it's funny in retrospect. There was a form field. "Any traffic violations in the last 2 years?" Self-declared. His ops team once did an internal audit of that field and the founder summarised the result to me as "fiction, politely formatted." Everyone ticked no. Obviously everyone ticked no.
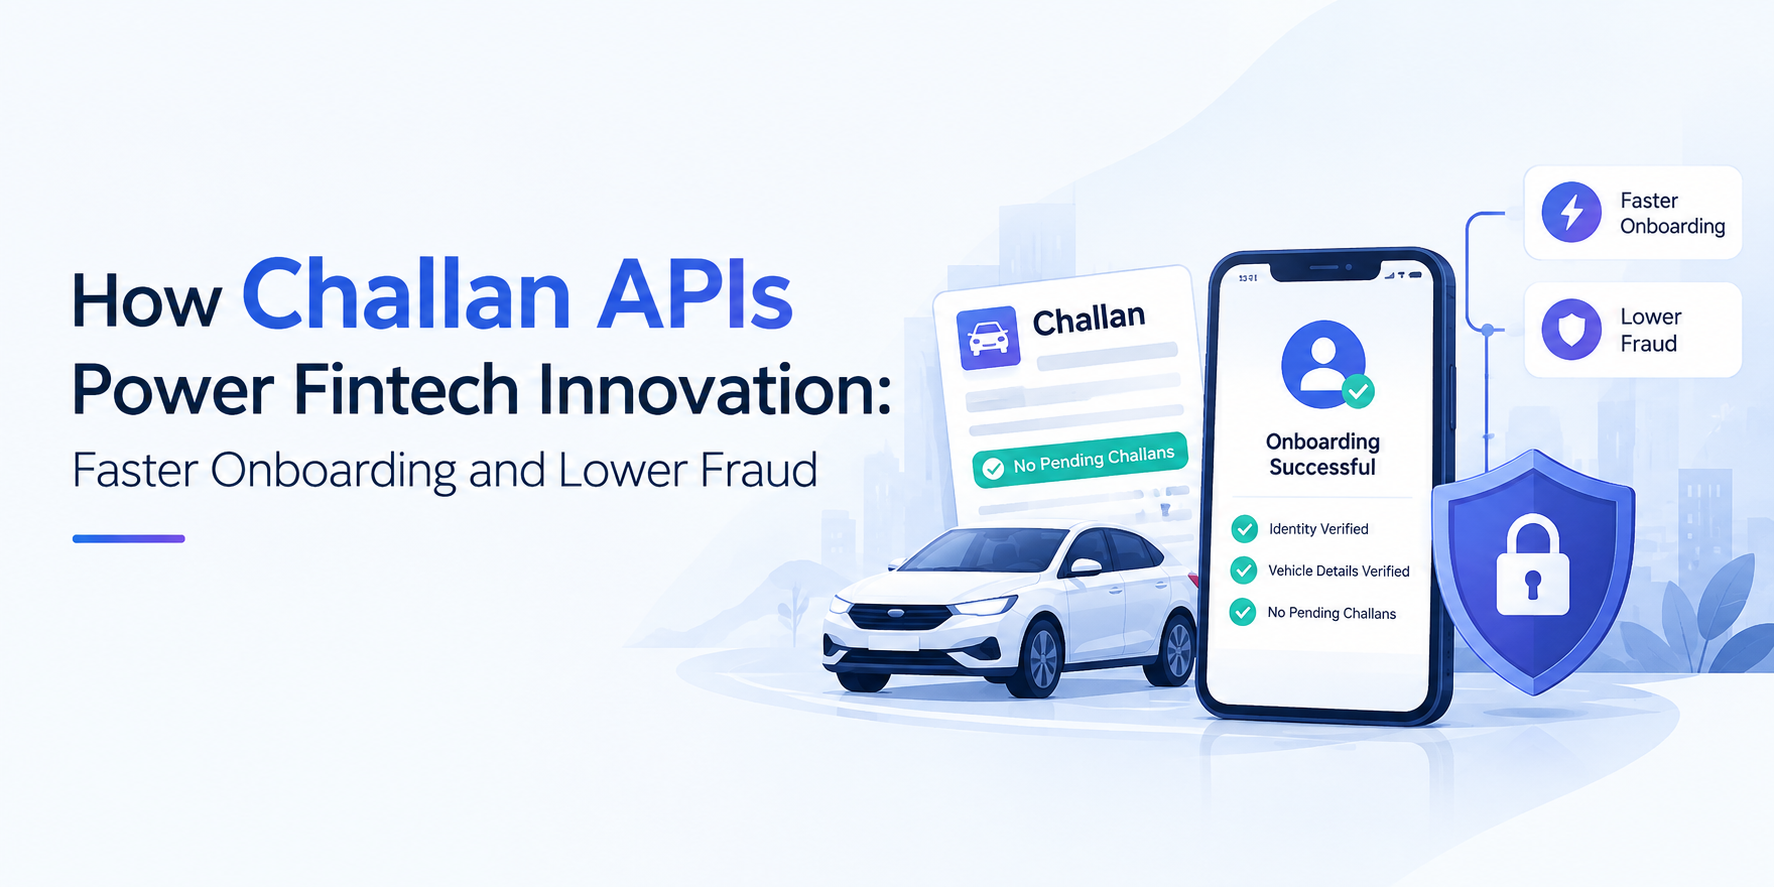
The replacement is almost anticlimactic. The challan API for fintech check fires while the applicant is still inside the app, takes under three seconds, and drops structured fields into the decision engine: count, amounts, dates, locations, status. The applicant never sees it. Clean files speed up, since nobody's asking honest riders to upload documents proving a negative anymore. The handful of contradictions, form says commute, fines say freight, go to a human with the discrepancy already highlighted.
That's it. That is the entire design of Challan API for fintech onboarding at his shop, and when people expect more I don't know what to tell them. The sophistication is in the restraint: night fines alone prove nothing, half his book is food-delivery riders whose job is night fines, so context does the deciding and a person does the declining. Consent gets taken before the call, every response is logged with a timestamp, the API security guide rules, all of it. He skipped proper logging in month one and an internal audit made the point for me, at length.
How challan APIs reduce fraud in fintech
People ask me how challan APIs reduce fraud in fintech and I give them the three cases I have personally watched get caught, in descending order of frequency.
The vehicle whose declared use is a lie. Personal scooter, commercial life. Most common, by a wide margin.
The vehicle whose possession is a lie. Rented out, informally sold, registration never moved. The apology-letter case above.
The vehicle being emptied before a default. Violations pile up in the final weeks while somebody extracts the last earning days from an asset they intend to surrender. Rarer, uglier, and visible in the data earlier than anywhere else.
The data convicts nobody, I want to be careful here. It points. A person picks up the phone. But it points early, and cheaply, and at things no other check even glances at. Provider selection is the fintech lending post checklist again, multi-state coverage above all, and the Digital Lenders Association of India is worth reading for how quickly this stack is spreading.
Conclusion
The scooter loan was declined and the man never disputed it, which said enough. My friend was right, I was wrong, and the best challan verification API for fintech companies turned out to be less a fraud tool than a truth tool: the one record of a vehicle's actual life, unrehearsable, readable in seconds, priced in single rupees. If you're building lending or insurance on vehicles and your Challan API budget line still says zero, you're where I was two years ago. It's a bad place to give advice from.